When a Strong Credit Rating Suffocates the Entrepreneur
By Dr. Nelson Jorge Mosco Castellano
Uruguay is living through a paradox that has become structural and threatens to bite into the productive heart of the country.
On the one hand, we proudly display the credentials of stability: a consolidated investment-grade rating, low country risk, and smooth access to international credit markets at favorable rates.
Global investors applaud. Credit rating agencies still look upon us favorably.
But when we lower our gaze from financial spreadsheets to the real economy —to the industrial plant, the agricultural producer, the technology entrepreneur’s warehouse, or the services exporter— the picture changes dramatically.
We are trapped in the labyrinth of exchange-rate overvaluation, a phenomenon of a “cheap dollar” that is not a meteorological accident, but the logical consequence of poorly calibrated macroeconomic balances.
And there is one leading actor in this movie that we often overlook: the constant issuance and placement of public debt.
The Bond Festival and the Flood of Foreign Currency
Every time the Uruguayan state goes out to issue debt —whether through global bonds denominated in foreign currency or other Treasury securities— it paradoxically achieves a financial success that punishes the productive economy.
How does this mechanism work? International and local investors buy those securities with fresh dollars.
That massive volume of foreign currency enters the domestic market.
When it is monetized to finance the needs of the state, it generates an artificial abundance of dollars that does not come from investment, and when it circulates as supply in the financial system and is converted into pesos, it increases the supply of dollars and artificially lowers the value of that currency.
The foreign exchange market responds to the basic laws of supply and demand: if there are too many dollars, the price falls.
In this way, the “excellent” credit reputation of sovereign Uruguay becomes a boomerang for the real exchange rate.
The state finances itself cheaply, but floods the market with greenbacks, pushing the dollar down and misaligning it from extremely high domestic costs in pesos, by the grace of the so-called “country cost.” In reality: tax costs and the suffocating burden of public prices.
In this case, the price of the dollar is a price artificially subsidized by the state itself to bankroll the debts promoted by politicians.
The Silent Victims: Exporters and Domestic Entrepreneurs
This mismatch does not come free of charge.
The impact on those who risk their capital in the tradable sector —those who compete with the world or who must export in order to grow— is relentless.
The Uruguayan exporter is trapped in a cost squeeze: sales are collected in dollars with a depressed nominal value, but operating costs are paid in pesos —wages, energy, fuel, public utility rates, freight and social charges— indexed in an economy that systematically becomes more expensive in real terms through the actions of the same political operator who later takes on debt to finance itself.
Profitability is compressed until it evaporates.
Competing in international markets with this structural exchange-rate overvaluation is equivalent to running the 100-meter dash with a backpack full of stones.
For the young entrepreneur trying to take off with an innovative project, a startup or an industrial SME, the “Uruguay cost” is a lethal barrier to entry.
The same is true for those looking for work and facing an insurmountable barrier in the labor, tax and regulatory costs paid by companies.
Without massive scale, facing a narrow domestic market and an exchange rate that erodes revenues against a rigid and expensive cost structure, the margin for survival is reduced to a minimum.
Financial timidity is rewarded, while productive muscle is punished.
The flight of domestic consumption abroad —the phenomenon of outbound tourism and massive border crossings— is the link that completes the chain of this imbalance, directly hitting the fabric of retail commerce and local services.
When the dollar is cheap and the peso appreciates strongly against regional currencies —or against the international cost of living— an unsustainable price distortion emerges:
Traveling abroad, shopping overseas or making purchases online becomes extremely cheap in relative terms.
Families and consumers transfer their purchasing power beyond the country’s borders, abandoning domestic commerce.
The Oddone solution: add VAT to the buyer trapped by the country cost who cannot travel.
The Agony of Border Commerce and Retail
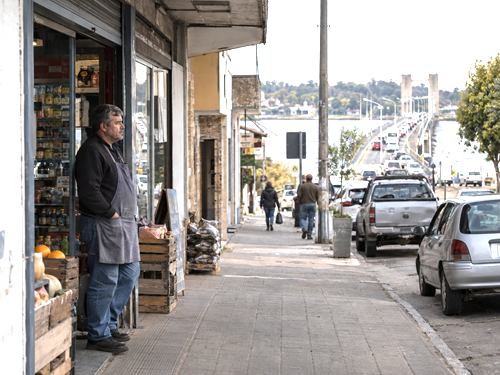
Cities along Uruguay’s western border suffer a dramatic impact when crossing the border becomes synonymous with saving dozens of percentage points on basic goods, clothing or food.
The local merchant finds himself in a situation of absolute helplessness: he has to pay wages, rent, taxes and utility rates at Uruguayan prices, while his potential customers cross the bridge to fill their shopping carts or vacation on the other side.
This diversion of spending is not harmless; it translates into a drastic loss of revenue for small merchants, destruction of jobs in the industrial sector, and a structural bias that allows those living in border areas to survive, to the detriment of those who invest and create jobs within the national territory.
The “miracle” of the cheap dollar, seen from this perspective, is actually a mirage: it subsidizes consumption abroad while draining the domestic market, leaving local merchants and service providers at the mercy of profoundly uneven competition.
Is There a Way Out of the Labyrinth?
The central problem is that we have become an expensive country with fragile economic foundations in our productive apparatus.
Nominal stability and the inflation anchor are defended at the cost of sacrificing external competitiveness.
If we want a Uruguay that genuinely grows and stops declining, that creates quality jobs and does not depend exclusively on financial lenders to suppress the exchange rate, the state must rethink the equation.
It is not a matter of decreeing artificial exchange-rate jumps, but of understanding that managing public spending, improving state efficiency and reducing the enormous barriers that hinder productivity are urgent priorities.
Otherwise, we will continue celebrating the applause of speculators who still lend to us, while shutting down, one by one, the engines of those who actually produce.
Structural exchange-rate overvaluation
Public debt and foreign currency
Competitiveness and country cost
Continue reading in Global Order and Geopolitics
Apoyá la continuidad de Perspectiva Liberal
Perspectiva Liberal es un espacio editorial independiente. Si valorás este trabajo y querés colaborar con su continuidad, podés hacerlo mediante un aporte voluntario a nuestra cuenta Prex.
Cuenta Prex: 13440